Je bent je ingevulde velden bij deze pagina aan het verwijderen. Ben je zeker dat je dit wilt doen?
You are erasing your filled-in fields on this page. Are you sure that is what you want?
Nieuwe Versie BeschikbaarNew Version Available
Er is een update van deze pagina. Als je update naar de meest recente versie, verlies je mogelijk je huidige antwoorden voor deze pagina. Hoe wil je verdergaan ?
There is an updated version of this page. If you update to the most recent version, then your current progress on this page will be erased. Regardless, your record of completion will remain. How would you like to proceed?
In Finding the Determinant we described the determinant as a function that assigns a scalar to every square matrix. The
value of the function in the original definition was given by cofactor expansion along the first row of the matrix. We also
observed, through examples, that cofactor expansion along any row or column produces the same value. Examples,
however, do not constitute a sufficient proof of equivalency of different cofactor expansions. In this section
we will prove that cofactor expansions along any row or column produce the same outcome. This result is
known as the Laplace Expansion Theorem. We will also prove several results concerning elementary row
operations.
Define \(A_{1j}\) to be an \((n-1)\times (n-1)\) matrix obtained from \(A\) by deleting the first row and the \(j^{th}\) column of \(A\). We say that \(A_{1j}\) is the \((1, j)\)-minor of
\(A\).
We want to follow the same pattern to define the determinant of a larger matrix. A distinct feature of this expression is the
alternating sign pattern. We want to preserve this feature as we increase matrix size.
Let \(A=\begin{bmatrix}a_{ij}\end{bmatrix}\) be an \(n\times n\) matrix. Define the determinant of \(A\) by
Naturally, we would like to condense this formula. To accomplish this, let
\[C_{1j}=(-1)^{1+j}\det {A_{1j}}\]
We will refer to \(C_{1j}\) as the \((1,j)\)-cofactor of \(A\). When we use the cofactor notation, the expression in Definition 1 turns into the
following:
This process of computing the determinant is called the cofactor expansion along the first row.
Cofactor Expansion Along the First Column
As we have observed in several examples in Finding the Determinant, cofactor expansion along the first column produces the
same result as cofactor expansion along the top row. We will now formalize the process of cofactor expansion along the first
column for an \(n\times n\) matrix and prove that this process produces the same result as our original definition of the determinant. Let \(A\)
be an \(n\times n\) matrix.
Define \(A_{i1}\) to be an \((n-1)\times (n-1)\) matrix obtained from \(A\) by deleting the first column and the \(i^{th}\) row of \(A\). We say that \(A_{i1}\) is the \((i, 1)\)-minor of
\(A\).
Define \(C_{i1}=(-1)^{i+1}\det {A_{i1}}\) to be the \((i,1)\)-cofactor of \(A\).
Let \(A=\begin{bmatrix}a_{ij}\end{bmatrix}\) be an \(n\times n\) matrix. Define the determinant of \(A\) by
We will proceed by induction on \(n\). Clearly, the result holds for \(n=1\). Just for practice you should also verify the equality for \(n=2, 3\).
(See Practice Problem ??.) We will assume that the result holds for \((n-1)\times (n-1)\) matrices and show that it must hold for \(n\times n\)
matrices.
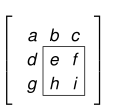
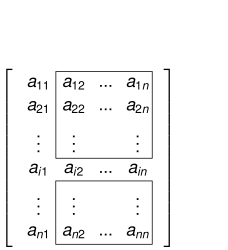
You will find the following matrix a useful reference as we proceed.
Note that the first term \(a_{11}(-1)^{1+1}\det {A_{11}}\) is the same for LHS and RHS, so we will only need to consider \(i,j\geq 2\).
We will start by analyzing RHS. Consider an arbitrary entry \(a_{i1}\) of the fist column. This entry will only appear
in the term \(a_{i1}(-1)^{i+1}\det {A_{i1}}\). We will find \(\det {A_{i1}}\) by cofactor expansion along the first row. As we proceed, we have to pay special
attention to the subscripts. Because the first column of \(A\) was removed, the \(j^{th}\) column of \(A\) contains the \((j-1)\) column of \(A_{i1}\).
Note that the entry \(a_{1j}\) will only appear in the term
\[a_{1j}(-1)^{1+(j-1)}\det {(A_{i1})_{1(j-1)}}\]
So, after we distribute \(a_{i1}(-1)^{i+1}\), RHS will contain only one term of the form
\[a_{i1}a_{1j}(-1)^{p+q}\det {(A_{st})_{pq}}\]
We will perform a similar analysis on LHS. Consider an arbitrary entry \(a_{1j}\) of the fist row. This entry will only
appear in the term \(a_{1j}(-1)^{1+j}\big (\det {A_{1j}}\big )\). Invoking the induction hypothesis, we will find \(\det {A_{1j}}\) by cofactor expansion along the first column.
Observe that \((A_{i1})_{1(j-1)}\) and \((A_{1j})_{(i-1)1}\) are the same matrix because both were obtained from matrix \(A\) by deleting the first and the \(i^{th}\) rows of \(A\), and
the first and the \(j^{th}\) columns of \(A\). Therefore \(\det {(A_{i1})_{1(j-1)}}=\det {(A_{1j})_{(i-1)1}}\).
We conclude that the terms of LHS and RHS match. This establishes the desired equality.
Now we know that cofactor expansion along the first row and cofactor expansion along the first column produce the same
result, so either expansion can be used to find the determinant.
Proof of Results Concerning Elementary Row Operations
In Elementary Row Operations we observed, without proof, the following properties of the determinant. (See Theorem
??
.)
Let \(A=\begin{bmatrix}a_{ij}\end{bmatrix}\) be an \(n\times n\) matrix.
1.
If \(B\) is obtained from \(A\) by interchanging two different rows, then
\[\det {B}=-\det {A}\]
2.
If \(B\) is obtained from \(A\) by multiplying one of the rows of \(A\) by a non-zero constant \(k\). Then
\[\det {B}=k\det {A}\]
3.
If \(B\) is obtained from \(A\) by adding a multiple of one row of \(A\) to another row, then
\[\det {B}=\det {A}\]
We now prove these properties.
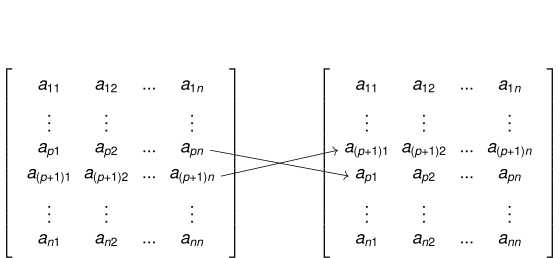
Proof of Theorem ??1 We will start by showing that the result holds if two consecutive rows are interchanged. Suppose \(B\) is
obtained from \(A\) by swapping rows \(p\) and \(p+1\) of \(A\).
We proceed by induction on \(n\). The result is not applicable for \(n=1\). In Practice Problem , you will be asked to verify that the result
holds for \(2\times 2\) matrices. Suppose that the result holds for \((n-1)\times (n-1)\) matrices. We need to show that it holds for \(n\times n\) matrices. You may find the
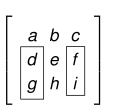
following diagram useful throughout the proof.
Observe that for \(i\neq p, p+1\) we have:
\[b_{ij}=a_{ij}\]
Because \(B_{ij}\) is obtained from \(A_{ij}\) by switching two rows of \(A_{ij}\), our induction hypothesis give us:
If two non-adjacent rows are switched, then the switch can be carried out by performing an odd number of adjacent row
interchanges (See Practice Problem ), so the result still holds.
Proof of Theorem ??2 We proceed by induction on \(n\). Clearly the statement is true for \(n=1\). Just for fun, you might want to verify
directly that it holds for \(2\times 2\) matrices. Now suppose the statement is true for all \((n-1)\times (n-1)\) matrices. We will show that it holds for \(n\times n\)
matrices.
Suppose \(B\) is obtained from \(A\) by multiplying the \(p\)’s row of \(A\) by \(k\).
Before we tackle the proof of Part 3 of Theorem ?? we will need to prove the following lemma.
Let \(A\), \(B\) and \(C\) be \(n\times n\) matrices. Suppose \(A\), \(B\) and \(C\) are identical, except for the \(p^{th}\) row. If the \(p^{th}\) row of \(C\) is the sum of the \(p^{th}\) rows of \(A\) and \(B\),
then
\[\det {C}=\det {A}+\det {B}\]
We will proceed by induction on \(n\). We leave it to the reader to verify cases \(n=1, 2\). We will assume that the statement holds for all \((n-1)\times (n-1)\)
matrices and show that it holds for \(n\times n\) matrices.
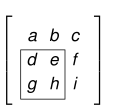
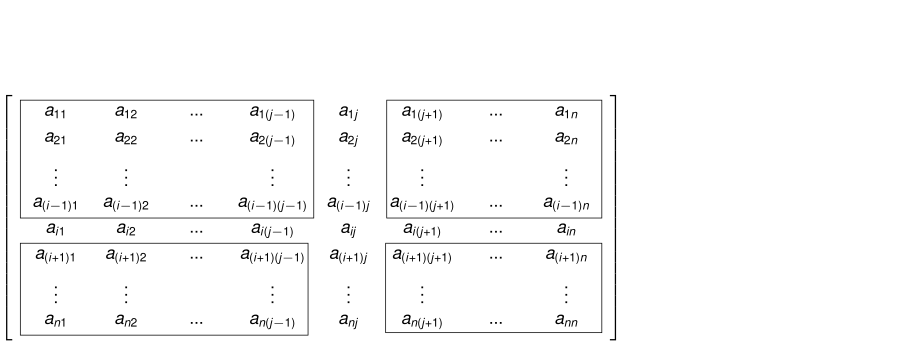
You may find the following representations of \(A\), \(B\) and \(C\) helpful. Identical entries in \(A\), \(B\) and \(C\) are labeled \(d_{ij}\).
We are now ready to finish the proof of Theorem ??
Proof of Theorem ??3 Suppose \(B\) is obtained from \(A\) by adding \(k\) times row \(p\) to row \(q\). (\(p\neq q\) and \(k\neq 0\)) You may find the following
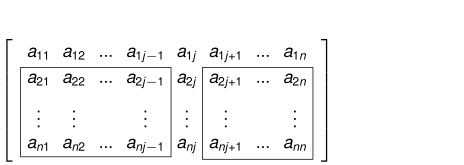
representations of \(A\) and \(B\) useful.
Observe that matrices \(A\), \(A'\) and \(B\) are identical except for the \(q^{th}\) row, and the \(q^{th}\) row of matrix \(B\) is the sum of the \(q^{th}\) rows of \(A\) and \(A'\). Thus,
by Lemma 8, we have:
\[\det {B}=\det {A}+\det {A'}\]
Since one row of \(A'\) is a scalar multiple of another row, we know \(\det {A'}=0\) (see Practice Problem ??). Therefore \(\det {B}=\det {A}\).
The Laplace Expansion Theorem
As we have seen in examples, the value of the determinant can be computed by expanding along any row
or column. This result is known as the Laplace Expansion Theorem. We begin by generalizing some earlier
definitions.
define the minor\(A_{ij}\) to be an \((n-1)\times (n-1)\) matrix obtained from \(A\) by deleting the \(i^{th}\) row and the \(j^{th}\) column of \(A\).
Define the \((i,j)\)-cofactor of \(A\) by
\[C_{ij}=(-1)^{i+j}\det (A_{ij})\]
Note that the sign of \((-1)^{i+j}\) follows a checkerboard pattern.
Laplace Expansion Theorem Let \(A=\begin{bmatrix}a_{ij}\end{bmatrix}\) be an \(n\times n\) matrix. Then each of the following computations produces \(\det {A}\).
We will start by showing that cofactor expansion along column \(j\) produces the same result as cofactor expansion along the first
column. Observe that column \(j\) can be shifted into the first column position by \(j-1\) consecutive row switches. Let \(A'=\begin{bmatrix}a'_{ij}\end{bmatrix}\) be the matrix
obtained from \(A\) by performing the necessary column switches. Then
To show that the determinant of \(A\) can also be computed by cofactor expansion along any row follows from the fact that \(\det {A}=\det {A^T}\).
(Theorem ??)
Practice Problems
Complete the proof of Theorem ???? by showing that the result holds for a \(2\times 2\) matrix.
Let \(p\) and \(q\) be two rows of a matrix, with \(p<q\). Show that the switch of \(p\) and \(q\) requires \(2(q-p)-1\) adjacent row interchanges.
 Linear Algebra: An Interactive Introduction